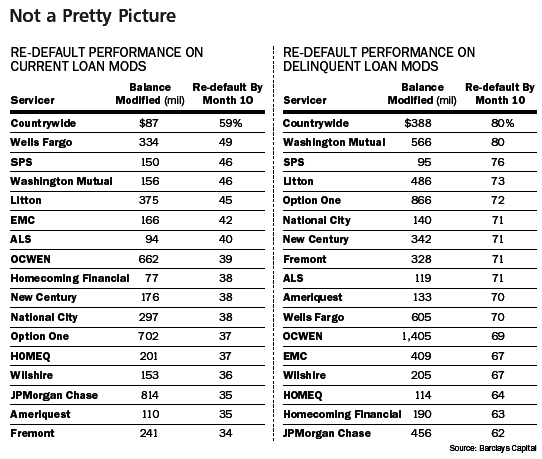
The chart provided above via Barron's via Mark Hanson via Hanson Advisors shows the futility of the current program of loan modifications. The Barron's article that this linked to article quotes from is a great editorial with perhaps the best quote I've heard in years, one which correctly pegs the current state of the housing markets:
“Loan mods are designed to keep the unpaid principal balances of the lender’s loans intact while re-levering the borrower. Mortgage modifications turn homeowners into underwater, overlevered renters for life, unable to sell, re-buy, refi, shop or save. They turn homeowners into economic zombies.” Mark Hanson
This quote gets it right on and echoes what I've been saying for over a year now. The loan modifications taking place right now and over the past months have been a ruse. They simply play "kick the can". The goal of the bank is to keep the loan on the books at full value even though the collateral is sometimes worth 50% less than the loan balance (or more). The mortgage services simply tacks on the past due balance, taxes and penalties on to the back end of the loan and lowers the interest rate and/or extends the life of the loan to 40 years. Take for example an individual with a home loan of $500,000 on a property worth $250,000 - they are six months behind on payments or about $35,000 including taxes. The loan mod will give them a new mortgage of $535,000 at a lower interest rate for a longer time period....thereby preserving the lenders balance sheet while increasing the total indebtness of the borrower - who couldn't afford the first loan. This situation makes a redefault highly likely and in fact that is what the numbers show....leading to Mark Hanson's above quote - these homeowners turn into "Economic Zombies".
The problem is not with loan modifications, its how they are being done. The bank balance sheets are the number one priority, not the homeowner, this leads to a situation where the market will take much longer to heal and foreclosures will be much greater and prices will overcorrect. What needs to happen is some government action, but not mass intervention. We need to incentive the servicers and lenders to modify those loans that are economically viable and WRITE DOWN PRINCIPAL and to immediately (following current law of course) foreclose on those where it makes no sense to allow them to stay in the home. In exchange for the balance sheet destruction the government can offer tax incentives and coordinate a national Property Appreciation Rights program that exchanges the debt on the property for equity. This will not fully offset the losses, but it shouldn't. Simply doing this will create a floor under prices in many areas and allow for inventory levels to normalize (some places would continue to fall until they hit equilibrium).
If we keep on the current path we will never be able to build a firm foundation going forward. Of course things have gotten so bad now that fixing housing will no longer fix the economy, but it is a needed first step.
Scott Dauenhauer CFP, MSFP, AIF
www.meridianwealth.com